Texas is often promoted as a tax-friendly retirement destination, and for good reason. The state does not impose a personal income tax, which can be appealing for retirees with substantial income from investments, business interests, pensions, or retirement accounts.
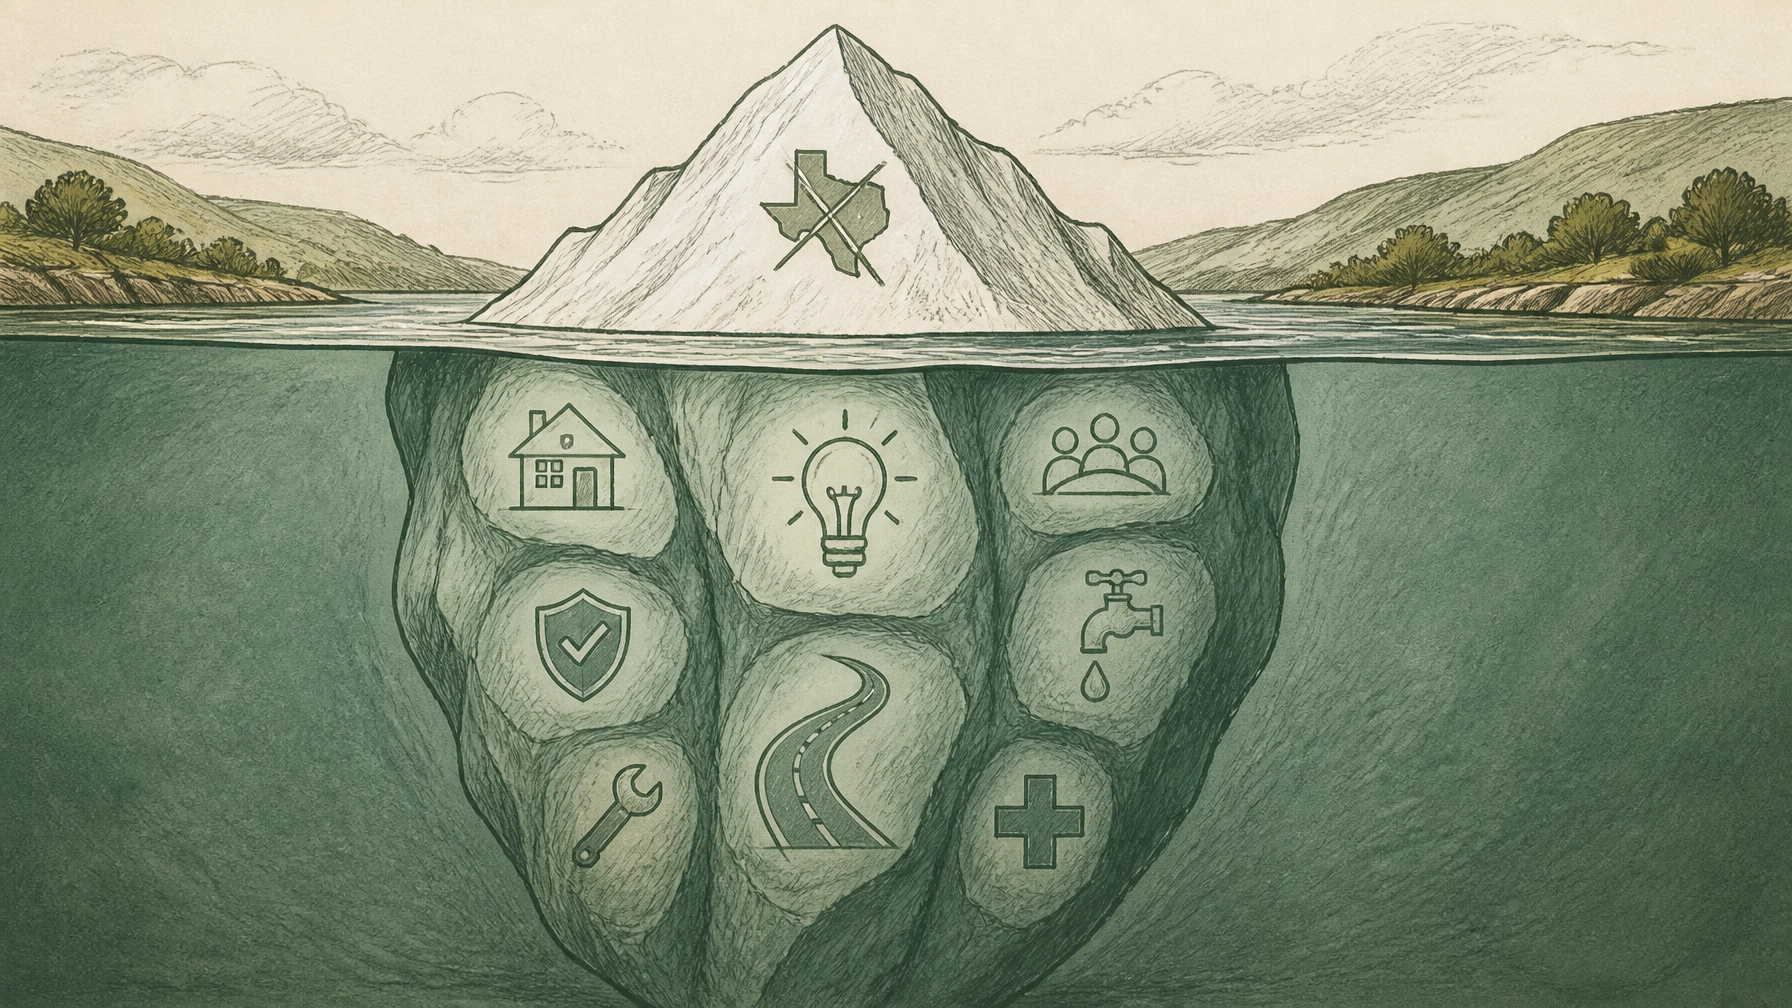
But “no state income tax” is only one line in a much larger retirement budget.
For someone considering a move to Dripping Springs, the more useful question is not, “How much will I save by moving to Texas?” It is:
How will my total cost of living change after accounting for housing, property taxes, insurance, utilities, transportation, healthcare, and lifestyle spending?
That broader comparison can help you make a more informed decision about peaceful Hill Country living without relying on a single tax headline.
Texas Has No State Income Tax, but That Does Not Mean No Taxes
The most widely known Texas tax feature is the absence of a state personal income tax. This may be particularly relevant for retirees relocating from states that tax wages, pensions, investment income, or other forms of personal income.
However, state revenue still has to come from somewhere. Texas relies more heavily on sources such as sales taxes, property taxes, and local fees. The result is that your personal experience may vary significantly depending on where you live, what you buy, and what kind of property you own.
Texas also does not have a state-level property tax. As the Texas Comptroller explains, “There is no state property tax.” Instead, property taxes are assessed and collected locally by entities such as counties, cities, school districts, and special districts.
That distinction matters in Dripping Springs.
A home may be subject to taxes from Hays County, a school district, the City of Dripping Springs if it is inside city limits, and other applicable districts. Two homes only a few miles apart may have different tax structures depending on their exact location and jurisdiction.
What to compare before purchasing
When reviewing a property, look beyond the listing price. Ask for:
- The current appraised value
- The most recent property-tax bill
- The taxing jurisdictions attached to the property
- Any homestead exemption currently applied
- Whether the home is inside city limits or in an unincorporated area
- Any applicable municipal utility, emergency services, or special-district charges
Texas offers homestead exemptions and appraisal protections for qualifying homeowners, including additional provisions for some homeowners age 65 and older. The Comptroller’s property-tax exemption guidance provides an overview, but your county appraisal district determines how the rules apply to your individual property.
Property Taxes Can Be More Meaningful Than Expected
A retirement home in Dripping Springs may offer more land, privacy, architectural character, and outdoor living space than a comparable home in a dense urban market. It may also have a higher taxable value.
This is especially important for buyers considering:
- Acreage or ranch-style properties
- Gated communities
- Custom homes
- Large outdoor entertaining spaces
- Pools, guesthouses, workshops, or detached structures
- Luxury homes near wineries, golf, and private amenities
The lifestyle may be exactly what you want, but the carrying costs can be different from those of a smaller suburban home.
It is also important to remember that property taxes are not the only recurring expense tied to the home. A property with extensive landscaping, long driveways, private roads, wells, septic systems, or large rooflines may require more ongoing maintenance than a conventional neighborhood property.
Our previous guide to Dripping Springs homeowners associations discusses another recurring cost: HOA dues. These fees may support trails, pools, security, landscaping, community programming, or other amenities, but they can increase over time and may be accompanied by special assessments.

Homeowners Insurance Is a Major Line Item
Insurance is one of the most important hidden costs for anyone moving to Texas.
According to the Texas Department of Insurance, the preliminary average annual homeowners insurance premium in Texas for 2025 was approximately $3,506 for policies with wind coverage. That is a statewide average, not a quote for Dripping Springs, but it illustrates why insurance deserves its own place in a relocation budget.
Texas homeowners insurance costs are influenced by factors including:
- Wind and hail exposure
- Wildfire and fire risk
- The age and condition of the roof
- Construction materials
- Replacement-cost estimates
- Distance from emergency services
- Claims history
- Deductible levels
- Availability of coverage in the local market
The Texas Department of Insurance reports that wind and hail have represented a significant share of homeowners’ losses in the state. Standard homeowners policies may also exclude flood damage, meaning separate flood coverage could be necessary depending on the property’s location and risk profile.
Before making an offer, obtain an insurance quote for the specific home. A general estimate based on another property, or a prior residence in another state, may not be reliable.
Also ask whether the property includes features such as a detached barn, guesthouse, high-value furnishings, extensive fencing, or specialized equipment. These may require additional coverage or endorsements.
Utilities Depend on the Address
Utility costs in the Dripping Springs area can be less predictable than newcomers expect because different properties may be served by different providers.
Electricity may come from Austin Energy, a cooperative, or another provider depending on the service territory. Water and wastewater service may be provided by the City of Dripping Springs, Austin Water, a water supply corporation, a special utility district, or a private well and septic system.
The City of Austin’s water and wastewater rates and Austin Energy’s approved rate schedules apply only to customers in those systems.
Meanwhile, the City of Dripping Springs has published wastewater rate adjustments, including a residential base wastewater fee and usage-based charges. The amount a household pays will depend on its provider, meter, consumption, and applicable fees.
For rural or semi-rural homes, utility planning may also involve:
- Well maintenance and water testing
- Septic inspections and pumping
- Private road or gate maintenance
- Propane delivery
- Backup generators
- Irrigation systems
- Long-distance utility connections
- Water conservation improvements
The best time to identify these costs is before closing: not after the first utility bill arrives.

Sales Taxes and Everyday Spending Still Matter
Even if your income is not subject to a state income tax, everyday purchases may be subject to sales taxes. Groceries, dining, home furnishings, vehicles, construction materials, entertainment, and personal services can all affect your monthly spending.
A move to Dripping Springs may also change how often you drive and how far you travel. Some retirees enjoy the quiet of a larger property, but that may mean more driving for:
- Medical appointments
- Shopping
- Restaurants and wineries
- Cultural events in Austin
- Airport travel
- Family visits
- Home and property services
A lower tax bill can be offset by higher transportation costs if the new home is farther from the places you visit regularly.
Healthcare deserves similar attention. Medicare premiums and out-of-pocket costs are not determined by Texas’s lack of state income tax. Your provider network, supplemental coverage, prescription needs, and access to preferred specialists may have a larger effect on your healthcare budget.
Compare the Lifestyle Cost, Not Just the Tax Rate
Dripping Springs can offer a slower pace, open skies, local wineries, trails, restaurants, art, and a strong connection to the Hill Country. Those benefits have real value: but they should be considered alongside the financial commitment required to maintain the lifestyle.
A useful comparison might look like this:
| Category | Current Location | Potential Dripping Springs Home |
|---|---|---|
| Housing payment or rent | ||
| Property taxes | ||
| Homeowners insurance | ||
| HOA or private-community dues | ||
| Electricity | ||
| Water and wastewater | ||
| Maintenance and landscaping | ||
| Transportation and fuel | ||
| Healthcare and prescriptions | ||
| Dining, travel, and recreation | ||
| Annual total |
This exercise does not need to produce a perfect forecast. Its purpose is to reveal categories that may be missing from a simple state-tax comparison.
It can also help you decide whether a particular property fits your retirement income plan. A home that looks affordable based on its purchase price may require more liquidity for taxes, insurance, upkeep, and lifestyle expenses.
Build Flexibility Into Your Retirement Plan
A sound relocation decision should account for changing costs over time. Insurance premiums may rise. Utility rates may change. Property values may increase. Home maintenance may become more expensive as the property ages.
That is one reason liquidity and proper portfolio construction matter. Retirement assets held in transparent, publicly traded markets can provide flexibility for recurring expenses and unexpected needs. A client-specific mix of long-term equity ownership and traditional fixed income may help support both current spending and future purchasing power, while avoiding unnecessary lockups, excessive fees, or complexity.
As Mau Sanchez has written in “Investing in Lifestyle: The Long-Term Value of Dripping Springs Real Estate,” a home should be viewed as part of your broader financial picture: not as a substitute for maintaining accessible assets that can fund your life.

The Bottom Line
Texas can be a compelling retirement destination, particularly for households that value Hill Country scenery, outdoor living, cultural experiences, and the absence of a state personal income tax.
But the strongest relocation decisions are based on the full picture.
Before moving to Dripping Springs, compare the total cost of ownership: not just the state tax rate. Review property taxes, insurance quotes, utilities, HOA dues, maintenance, transportation, healthcare, and the lifestyle expenses you realistically expect to enjoy.
The goal is not to prove that Texas is always cheaper. The goal is to understand what you are actually buying: a home, a community, and a way of life that should fit comfortably within your broader retirement plan.
Schedule a private meeting with a fiduciary financial advisor today by calling (512) 593-8380 or by visiting: https://calendly.com/portafoliocapital/15min
Portafolio Capital Management dba Mau Sanchez Capital is a Registered Investment Adviser. This content is for informational purposes only and does not constitute investment advice or a solicitation to buy or sell any security. Advisory services are provided only pursuant to a written advisory agreement.
To learn more about Portafolio Capital Management dba Mau Sanchez Capital, visit https://portafoliocapital.com/ or call (512) 593-8380.
This article may include stories, scenarios, and perspectives created or assisted by artificial intelligence. Although the individuals and circumstances described may be fictional, the topics are intended to reflect real financial, personal, and lifestyle issues that retirees and individuals commonly face.
The content is provided to encourage readers to consider different perspectives that may affect their retirement, regardless of whether they are currently planning, approaching retirement, or already retired. It is intended for general educational and informational purposes only and should not be interpreted as personalized investment, financial, tax, legal, medical, or retirement-planning advice.
Individual circumstances vary. Readers should independently verify any information presented and consult appropriately qualified professionals before making financial or personal decisions. No advisory, professional, or client relationship is created through the use of this website.
Leave a Reply